M&Y Personal Injury Lawyers Helps Secure Record $198.1 Million Verdict in Tragic California Crash Case

Free Consultation, Talk to a Real Lawyer Now.

What is Property Damage?

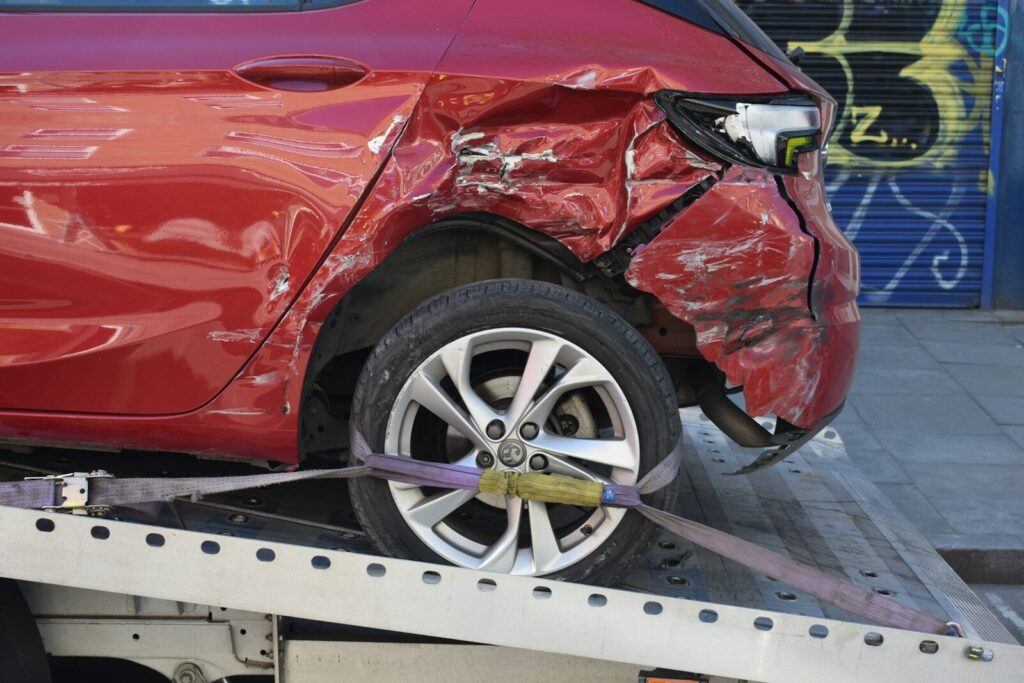
Property damage is physical harm to a vehicle or other personal property that creates repair costs, loss in value, or replacement costs. It is distinct from bodily injury, which involves harm to a person.

A California car accident can create both a property-damage claim and a separate personal injury claim. The two claims involve different types of loss and different filing deadlines.

Table of Contents

Who Pays for Property Damage After a California Car Accident?

A person fills out a form on a clipboard while standing next to a car with a shattered windshield, possibly documenting accident details.

The source of payment for vehicle damage after a crash depends on the available insurance coverage and the facts of the collision. Two types of coverage are most relevant.

How Does the At-Fault Driver’s Liability Coverage Work?

California automobile liability coverage includes property-damage liability that can pay for qualifying damage the insured is legally responsible for causing to another person’s property. The amount available depends on the policy limits purchased.

For policies or bonds subject to Vehicle Code § 16056, the minimum property-damage liability limit is $15,000 per accident as of January 1, 2025. That is a statutory minimum, not a maximum. Some drivers carry higher limits.

A property-damage liability limit caps what the at-fault driver’s policy pays for covered damage from a single accident. When the actual damage exceeds that limit, the policy does not cover the difference.

What About a Person’s Own Collision Coverage?

A person’s own collision coverage can also apply to vehicle damage after a covered crash, subject to the policy terms and deductible. Collision coverage pays for damage to the policyholder’s own vehicle regardless of fault.

Not every driver purchases collision coverage. Whether it applies depends on the specific policy in effect at the time of the crash.

What Property Damage Can You Recover After a Car Accident?

Property-damage recovery depends on what was damaged, whether it can be repaired, and the applicable legal or insurance framework. For automobile crashes, the most common categories of recoverable loss include:

  • Reasonable vehicle repair costs
  • Remaining loss in market value when repairs do not fully restore the vehicle’s pre-crash value
  • Fair market value when the vehicle is a total loss
  • Towing, storage, or loss-of-use damages, which can reflect the reasonable rental value of a similar vehicle for the time reasonably needed to repair or replace it
  • Damage to personal property inside the vehicle when supported by evidence of ownership, condition, and value

Not every category applies in every case. What is recoverable depends on the specific facts, the type of claim, and whether recovery comes through insurance or a legal action against the responsible party.

How Does California Measure Damage to a Vehicle?

California’s tort measure for injury to personal property generally starts with the lesser of the reduction in value or reasonable repair cost. The current California Civil Jury Instructions, CACI No. 3903J, addresses how vehicle damage is calculated in a legal claim.

When repairs fully restore the vehicle’s market value, reasonable repair costs can measure the loss. When repairs leave a remaining loss in market value, CACI 3903J permits recovery of reasonable repair costs plus that remaining diminished value.

The combined amount of repair costs and remaining loss in value cannot exceed the vehicle’s pre-loss fair market value. These tort-damage rules apply to claims against a responsible party. They do not override contractual terms in a person’s own insurance policy. 

What Happens If the Vehicle Is a Total Loss?
M&Y Personal Injury Lawyers LogoA vehicle is treated as a total loss when repair or restoration to the pre-loss condition would involve unreasonable cost. The  California Department of Insurance defines total loss based on unreasonable repair cost relative to the vehicle’s value.

Under standard auto physical-damage coverage, actual cash value generally means fair market value unless the policy defines it differently. Valuation can consider factors such as the vehicle’s year, make, model, mileage, condition, and comparable market data.

A vehicle’s insurance valuation and the owner’s outstanding loan balance are separate figures. When the loan exceeds the vehicle’s value, the total-loss payment may not cover the remaining balance.

What Documents Help Support a Property Damage Claim?

Records that show what was damaged, when the damage occurred, and the amount of loss help support a property-damage claim. The type and detail of documentation can affect how the claim is evaluated.

Useful records include:

  • Photographs of the vehicle and other damaged property taken after the crash
  • Repair estimates from qualified shops and final invoices for completed work
  • Towing and storage receipts
  • Documentation of vehicle condition, mileage, options, and prior damage when valuation is disputed
  • Receipts or proof of ownership for personal property damaged inside the vehicle

Each type of record addresses a different part of the claim. Photographs document the location and visible extent of damage. Estimates identify proposed repairs and costs. Vehicle-condition records help evaluate market value when total loss or remaining diminished value is disputed.

Can More Than One Person or Company Be Responsible for Property Damage?

Responsibility for property damage can involve more than one person or business when the evidence shows multiple parties contributed to the crash. Identifying all potentially responsible parties matters before resolving the claim.

Responsibility can extend beyond the driver when the evidence and applicable law support liability against an employer or vehicle owner. No party is automatically liable simply because they are connected to the crash. The evidence must support each party’s responsibility.

What If the Property Damage Costs More Than the Available Insurance?

When vehicle damage exceeds the at-fault driver’s property-damage liability limit, that policy does not cover the difference. The injured person’s options depend on the available coverage and the circumstances.

Possible avenues include the person’s own collision coverage if purchased and applicable, a claim against another legally responsible party when the evidence supports it, or a direct claim against the responsible individual. If the person’s own insurer pays a covered collision claim, the insurer may pursue subrogation against the at-fault party.

A judgment against an at-fault driver does not by itself establish that the driver has assets to satisfy it.

How Long Do You Have to File a Property Damage Lawsuit in California?

Blue badge with the BBB Accredited Business torch symbolCalifornia generally provides three years to file a lawsuit for injury to personal property after the claim accrues. Code of Civil Procedure § 338(c)(1) supplies that limitations period.

The property-damage and personal-injury claims are subject to separate statutory limitations periods. Most qualifying personal-injury actions have a two-year limitations period after accrual under Code of Civil Procedure § 335.1.

For claims subject to California’s Government Claims Act, Government Code § 911.2 generally requires an initial claim for injury to personal property within six months after accrual. Missing that initial deadline can jeopardize the claim and trigger additional procedures. Exceptions and other procedural rules can affect all of these deadlines. 

Do You Need a Lawyer for a Property Damage Claim?

Many routine vehicle-damage issues can be handled through an insurance claim without legal representation. Legal review becomes more relevant when a crash also causes bodily injuries, liability is disputed, several parties may be responsible, or the property issues affect a broader injury claim.

When a collision causes bodily injuries as well as vehicle damage, our car accident lawyers evaluate the injury claim alongside the available property damage and insurance information. One attorney manages each accepted case from the first call through resolution.

FAQs About Property Damage Claims

Can I choose my own repair shop after a California car accident?

Yes. California Insurance Code § 758.5 restricts insurers from requiring repairs at a specific automotive repair dealer. The vehicle owner selects the repair facility. The insurer’s estimate and the chosen shop’s estimate may differ, and those differences can require further discussion.

A repair shop may discover additional damage after disassembly that was not visible during the initial inspection. When that occurs, the shop prepares a supplemental estimate. The insurer reviews the supplement to determine whether the additional repairs are covered under the applicable claim or policy.

Yes. If the insurer’s valuation does not reflect the vehicle’s actual pre-crash fair market value, the owner can provide comparable vehicle listings, maintenance records, or other documentation to support a higher valuation. California’s auto claims regulations require insurers to use market-based methods when valuing comparable automobiles.

Yes, in some cases. California allows an owner to retain a totaled vehicle, but doing so can affect the settlement amount and the vehicle’s title status. The insurer deducts the salvage value from the total-loss payment when the owner keeps the vehicle.

California measures loss-of-use damages based on the reasonable rental cost of a comparable vehicle for the time reasonably needed to repair or replace the damaged one. The applicable period depends on how long repairs take or how long it reasonably takes to replace a totaled vehicle. 

When Vehicle Damage Is Part of a Bigger Picture
Two people sit at a table with a document, one gesturing and the other signing. A judges gavel rests nearby, suggesting a legal or official context.Property damage after a car accident often accompanies bodily injuries, disputed liability, and questions about available insurance. Evaluating the vehicle damage alongside the injury claim helps identify every applicable source of recovery.

At M&Y Personal Injury Lawyers, we review the crash evidence, repair or valuation records, and insurance information when a collision involves both property damage and personal injuries. Consultations are free with no obligation.

Call 866-864-5477 for a free consultation. Our phones are answered 24 hours a day, seven days a week. Clients do not owe attorney fees unless compensation is recovered on their personal injury claim.